Start—
Interest carries more of the payment.
- Principal
- —
- Interest
- —
Home & mortgages
A mortgage shapes the monthly room around everything else. Explore payment, renewal and prepayment decisions with your numbers and transparent Canadian assumptions.See how payment, renewal and prepayment decisions shape the month around your home.
No lender pitch. No approval claims. Just clearer mortgage trade-offs.
Start with a question
Start with the decision your household is carrying now.
See how a payment changes over time
Part covers interest. Part reduces the mortgage balance. Over time, that mix changes.
Illustrative $500,000 mortgage at a 4.5% fixed nominal annual rate, semiannual compounding, 25-year amortization and monthly payments. Equal-period educational model; lender timing, rounding and posting may differ. Fees, taxes and insurance are not included.
Interest carries more of the payment.
The two parts move closer together.
More of the payment reduces balance.
Mortgage anatomy
Cost, commitment, repayment time and payment rhythm work together.
One mortgage. Four connected parts.
Each part changes how the payment and timeline behave.
What borrowing costs.
How long the current mortgage agreement lasts.
How long the balance is scheduled to take to repay.
How often payments are scheduled.
Built around real life
Housing costs sit beside debt, savings, emergencies, education goals and everything else competing for household cash flow.
The payment arrives every month. Life keeps moving around it.
Use your numbers
Open a current public tool and change the inputs yourself.
What cash is still needed, and how would this home fit the month?
Open Home-Buying Budget → Monthly costMortgage PaymentEstimate payments using balance, rate, amortization and frequency.
Open Mortgage Payment → Upcoming termMortgage RenewalExplore payment and term choices for your upcoming renewal.
Open Mortgage Renewal → Extra principalMortgage PrepaymentSee how extra payments affect payoff timing and interest.
Open Mortgage Prepayment →Canadian mortgage context
FinForFam’s fixed mortgage estimates use a fixed nominal annual rate with semiannual compounding, then model payments at the selected frequency.
Read our mortgage methodology01 · SchedulePayment timingEqual periods, paid in arrears for the educational schedule.
02 · PrecisionCent roundingPayments and each schedule event are handled in cents.
03 · ReconciliationReal statementsLender timing, rounding and posting can produce differences.
Assumptions matter
Keep the main levers visible, then change one at a time to understand what moves.
Read our methodologyThe principal being modelled.
The fixed nominal annual rate used.
The scheduled repayment horizon.
How often payments are scheduled.
The bigger picture
Housing costs affect cash flow, savings capacity, education goals, debt decisions and retirement planning.
FinForFam helps you keep the whole household picture in mind.
See your financial picture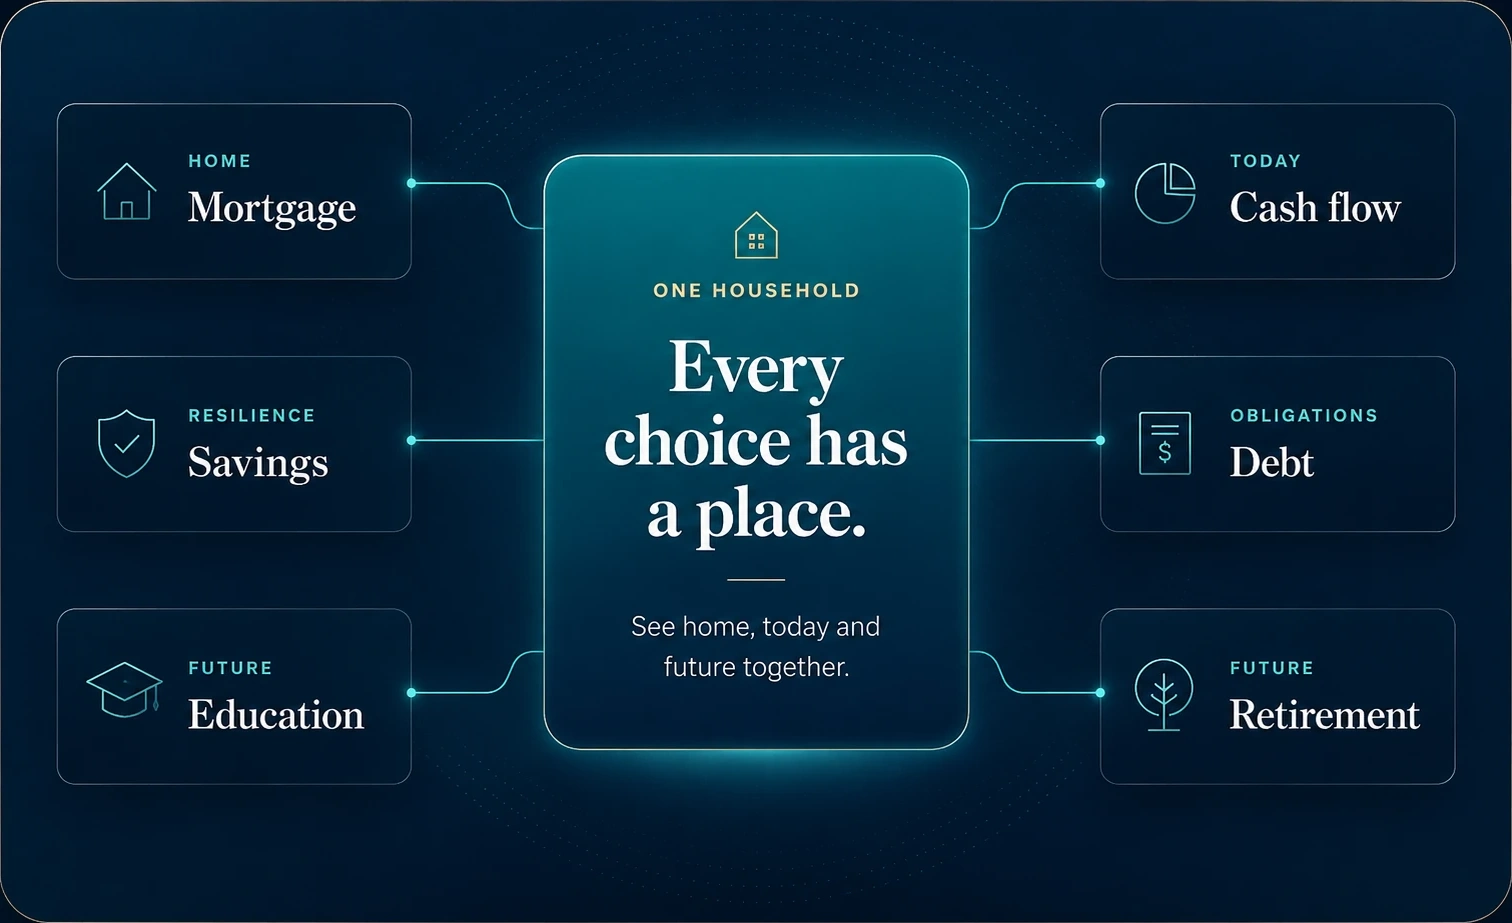
How it works
Payment, renewal or prepayment.
Balance, rate, amortization and timeline.
Understand what changes before deciding.
Understand before you decide